EXALUNE
Rebuilding Everyday Life
Budgeting after a separation: which costs should you plan for?
Regular bills, one-off costs and shared commitments: building a workable transition budget without solving everything at once.
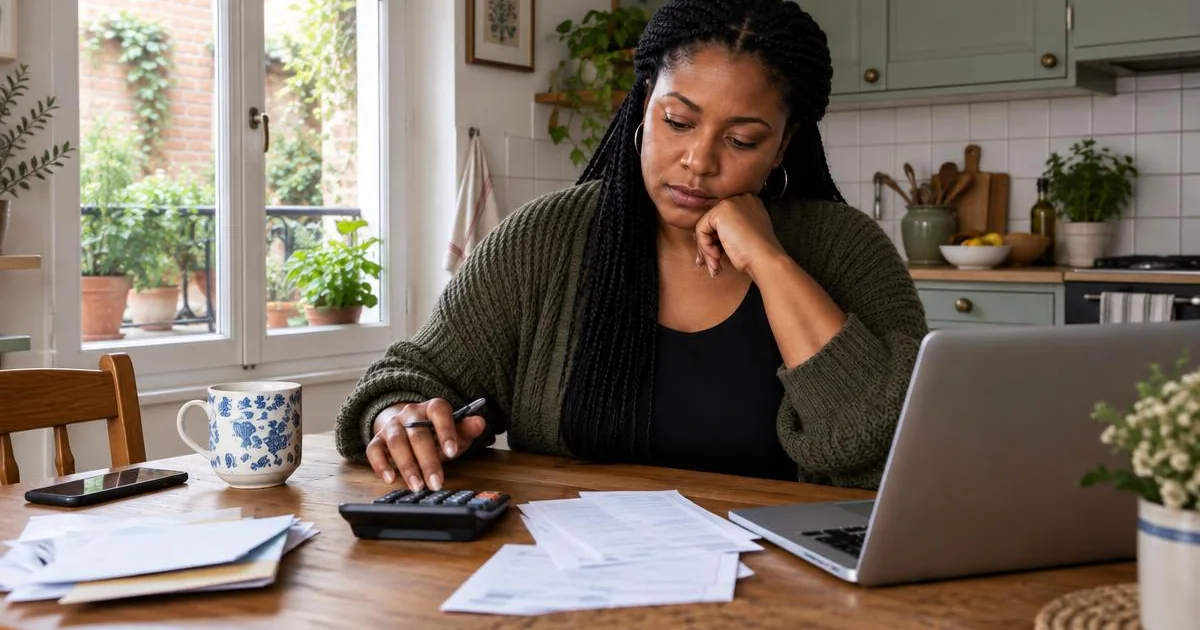
After separation, the same income may no longer support the same everyday life. Some expenses disappear, others are duplicated, and several remain shared for a while. Even if you previously felt confident about money, the picture can suddenly become difficult to read. The goal is not perfect financial discipline or predicting every expense. It is to understand what is available, what needs paying, and what still requires clarification. A useful budget creates enough visibility to make decisions without turning every purchase into a reason to feel guilty.
Start with the money that is genuinely available
Use recent statements, bills, contracts, repayment information, and income records that you are entitled to access. Separate personal funds, shared funds, and amounts whose availability is uncertain. The balance shown in an account may include money needed for pending payments or bills that have not arrived yet.
Look beyond the obvious monthly charges. Deferred card payments, instalment purchases, annual subscriptions, overdrafts, and guarantees can all affect the picture. If information is missing, identify the gap rather than filling it with a hopeful estimate. This first overview is about knowing what needs checking. It does not require you to reconstruct the entire financial history of the relationship or settle responsibility for every past decision.
Separate ongoing, transitional, and irregular costs
Ongoing expenses keep daily life functioning: housing, food, transport, insurance, communications, and children’s needs where relevant. Transitional costs arise because circumstances are changing, such as moving, essential equipment, administrative fees, or overlapping housing expenses. Irregular costs return less frequently, including maintenance, renewals, or some school expenses.
These categories matter because the first month may not represent your future budget. It may be unusually expensive, or look misleadingly manageable because larger bills will arrive later. Where possible, spread the expected cost of irregular essentials across the year when judging affordability. A bill being absent this month does not mean its share of your income is safely available for a new recurring commitment.
Prioritise the decisions that make the biggest difference
When money is tight, focus first on practical essentials: somewhere to live, food, energy, necessary transport, required care, and the needs of anyone dependent on you. Contractual obligations and court-ordered payments also need specific attention. If you cannot cover several commitments, local debt or legal advice can help establish appropriate priorities.
Cancelling unused subscriptions can help, but it may not solve a budget dominated by unaffordable housing or lost income. Avoid blaming yourself for every small purchase when a much larger structural cost explains the shortfall. Concentrate on changes that materially improve the situation. If possible, retain a little room for ordinary living rather than creating a plan so restrictive that it is difficult to sustain.
Distinguish who pays from who is legally responsible
The person currently paying a bill is not necessarily the only person responsible for the contract. Equally, a private agreement to split a payment may not change what a lender or provider can require. For shared commitments, establish whose name is on the agreement, who pays now, and what remains unresolved.
The legal position can depend on your country or region, relationship status, type of debt, and contractual terms. Marriage, civil partnership, and cohabitation do not have identical consequences everywhere. Obtain local advice about disputed debts, overdrafts, or major commitments. Do not stop an important payment solely because your former partner has said they will take over. Confirm whether the provider has accepted the relevant change.
Use a transition budget before a long-term one
Create a realistic picture of the changeover period and another of everyday life once the main changes have happened. Base immediate commitments on confirmed income. An application for support, a possible sale, or a promised repayment is not yet money available to spend.
For example, a future rent payment may be affordable while the deposit, moving costs, and remaining shared bills are not affordable together. That is partly a timing problem, not necessarily proof that the new home is unsustainable. Recognising the difference helps identify targeted options: delaying a nonessential purchase, asking whether a payment can be spread, or reconsidering how the move happens. Any arrangement needs confirmation before you rely on it.
Check support and administrative changes
Separation may affect information held by public bodies or service providers, including your address, household composition, children’s living arrangements, or assessable income. What must be reported and how it changes your position depends on local rules. Ask the relevant organisation rather than assuming records will update automatically.
Depending on where you live, it may be worth checking housing assistance, income-related support, reduced tariffs, or independent budgeting advice. Tax and insurance arrangements may also need review. Keep confirmations and distinguish an online estimate from an actual decision. If an explanation is unclear, ask how it applies to your circumstances before building the amount into your budget. Do not assume support will be granted simply because your costs have increased.
Prevent avoidable costs from multiplying
Missed payments, duplicated contracts, and forgotten automatic charges can make a difficult period more expensive. Compare the timing of income with payment dates. If a mismatch creates problems, contact the provider to ask what options exist. A changed payment date or temporary arrangement is not guaranteed, but an early conversation may be useful.
Check particularly for:
- charges still connected to the previous household;
- payments leaving a shared account;
- subscriptions now used by only one person;
- insurance that no longer matches the circumstances;
- recurring purchases attached to an old card.
Before cancelling anything, check possible fees, notice requirements, and continuity of essential services. An immediate saving can be misleading if it leaves you without necessary cover or creates a larger replacement cost.
Keep the system manageable
You do not need to monitor every purchase constantly. Accessible documents, a clear list of commitments, and a regular opportunity to review changes may be enough. Creating a routine can give financial administration a defined place rather than allowing it to occupy every day.
Money can also carry anger, shame, or fear. Those feelings do not demonstrate that you are managing badly. The emotional journaling guide can help you recognise them separately from the figures. If essential costs remain impossible to cover, seek suitable local support promptly. A budget is a decision-making tool, not a judgment on your worth. Its purpose is to make real needs visible and help you find workable next steps.
Official information for your country
Legal, banking and administrative rules depend on where you live and your circumstances. These general suggestions are not legal advice. Check the scope of each source and consult a qualified local professional where needed.
Going through this right now?
Answer a few questions to see where you stand, and receive a first exercise to move forward, at your own pace.
Free · No credit card · The articles stay freely available; the Journal requires an account and some activities are Premium.
These suggestions are not medical advice. If distress is persistent, overwhelming or affecting your safety, reach out to a qualified professional or a trusted person.